Don’t Gift Your Old Gold to Making Charges — Twice: Sell Gold in Delhi to Gold valuer, Don’t Just Exchange
September 8, 2026
Valuation Requirements for High-Value Gold Jewellery Under Indian Tax Rules: Sell Gold in Yusuf Sarai with a Record You Can Defend
September 10, 2026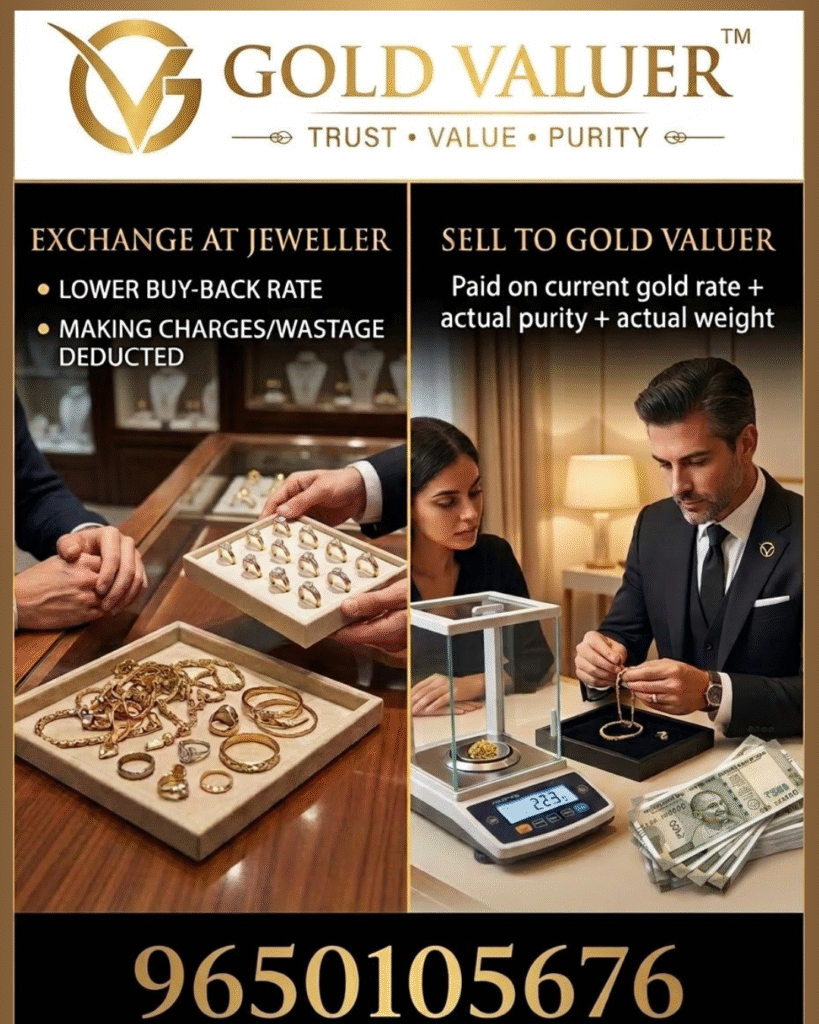
A gold loan looks simple. You take jewellery to a bank or NBFC. They test it. They weigh it. They offer a limit. You walk out with money and leave the gold behind. The part families in Haldwani miss is this: the loan is not against “your jewellery as you remember it.” It is against a lender’s assessed metal value, then cut again by a loan-to-value cap.
That is why Gold valuer talks to people before they pledge, and again when they decide a loan is the wrong product. If you need cash for gold in Haldwani, if you are comparing gold buyers in Haldwani, or you searched sell gold near me because interest and lock-in do not suit you, get an independent figure first. Do not let the first counter you enter decide both the value of your gold and the product you take.
This is a promotional guide. The offer is plain. Know how lenders value gold. Protect yourself. Then choose pledge or sale with Gold valuer in Haldwani.
Sell Gold Near Me or Take a Gold Loan? Haldwani Families Should Separate the Two
Sell gold near me is a sale search. A gold loan is a borrow search. Shops, agents, and even well-meaning relatives mix them. “Put it in the bank, take money, take it back later.” That sentence is true only if you can service the loan and collect the jewellery on time. If you cannot, the same gold is auctioned under lender rules, not under your family timeline.
Gold valuer asks one question at the door: do you want the gold back, or do you want the value in hand?
- If you want the gold back, understand the bank or NBFC valuation and LTV.
- If you want the value in hand, sell gold in Haldwani as metal: current rate, actual purity, actual weight.
- If you are unsure, take an independent valuation first. Then walk into the lender with a number you already understand.
That sequence is how you protect yourself. The lender is not your valuer-for-life. The lender is pricing collateral.
How Banks and NBFCs Value Gold Before They Lend
Regulated lenders in India do not pay making charges, design premium, or stone value. They price intrinsic gold. Under the Reserve Bank of India’s framework for lending against gold collateral, the idea is consistent across banks and NBFCs: assay purity, take net metal weight, apply a reference price, then lend only a percentage of that assessed value.
In practice, the desk does five things.
1. Accepts only eligible collateral
Jewellery and ornaments of acceptable purity are the usual security. Stones, threads, tips, and non-gold parts are out of the value. Making charges are out. The necklace you paid extra for as “workmanship” is, for the loan, a net-gold problem.
2. Tests purity
A karat meter or similar assay is used. Hallmark helps speed. It does not replace the lender’s check. Mixed family lots from Haldwani lockers — old sets, repaired items, unmarked pieces — get priced at the tested carat, not at the story on the box.
3. Weighs gross, then arrives at net gold
Gross weight is what the scale shows with everything on it. Net gold is what remains after non-gold deductions. Loan value sits on net gold.
4. Applies a reference rate, not a jeweller’s selling rate
RBI directions require valuation off a published reference price linked to purity — generally the lower of the previous day’s closing price and a 30-day average from IBJA or a SEBI-recognised exchange. That is why a borrower hears “today’s shop rate” and still sees a lower assessed value. The lender is not using the retail ticket.
5. Cuts again with LTV
Assessed value is not the loan. Maximum loan-to-value on consumption gold loans is tiered: up to 85% for loans up to ₹2.5 lakh, 80% between ₹2.5 lakh and ₹5 lakh, and 75% above ₹5 lakh. A lender may offer less. The cap is a ceiling, not a promise.
So the protective reading is: purity × net weight × reference rate = assessed value. Then LTV. Then charges and product terms. If anyone in Haldwani quotes “per gram loan” without showing those steps, you are shopping slogans.
Cash for Gold in Haldwani vs a Bank or NBFC Limit
This is the comparison Gold valuer wants on the table.
A gold loan gives you a slice of assessed value and keeps the jewellery.
A sale through a valuer can give you the metal proceeds and ends the relationship.
| You need | Loan desk | Gold valuer sale |
|---|---|---|
| Jewellery back later | Possible if you repay | No — you sold it |
| Maximum money now | Limited by LTV and reference rate | Paid as a sale on tested metal |
| Interest and tenure risk | Yes | No |
| Auction risk on default | Yes | No |
| Making charges in the number | No, and that surprises people | No, and that is disclosed as metal pricing |
| Independence | Lender prices its own collateral | You see test and weight as a seller |
Cash for gold in Haldwani is the right product when the gold is extra, outdated, disputed, or when EMI risk is higher than the sentimental need to retrieve the set. A loan is the right product when the jewellery must return to the same locker.
Do not use a loan to avoid the emotional word “sell” if you already know you will not redeem. That is how pledged gold becomes someone else’s auction lot.
Gold Buyers in Haldwani: Why an Independent Valuation Protects You at the Lender Too
Even if you finally pledge, an outside check helps. Banks and NBFCs follow their method. You still need a second pair of eyes on purity and weight before you sign.
Gold valuer is useful here as gold buyers in Haldwani who start as valuers:
- You see a purity result explained in plain language.
- You see weight on a scale in front of you.
- You get a payable-style metal figure you can compare with the lender’s assessed value and offered limit.
- You decide: pledge the lot, sell part, or sell all.
Without that, the first institution you visit becomes the only story you hear. In a small city, that is how people accept a low net-weight call or a conservative carat and still feel grateful for “instant money.”
Independent valuation is not hostility toward banks. It is self-defence.
What to Demand on Paper When You Pledge
RBI conduct rules push lenders toward standardised assay, valuation, and documentation. Borrowers should use that. Ask for the purity and valuation record at sanction: karat, gross weight, net weight after deductions, and assessed value. Keep the copy. That paper is what you argue from later if redemption, partial release, or auction becomes a fight.
Also read, before you sign:
- Whether stones were deducted and by how much
- Which rate basis was used
- LTV applied and whether it will be watched during the tenure
- Interest, penal charges, and tenure
- Auction notice rules if you default
- How surplus after auction, if any, comes back
If the branch cannot show the breakup, pause. Go to Gold valuer. Re-weigh the idea of pledging at all. Sometimes the better Haldwani move is to sell gold in Haldwani and stop the clock.
How to Protect Yourself Before You Hand Over the Pouch
Protect the decision, not only the receipt.
- Separate heirloom pieces from sale-or-pledge pieces at home. Do not empty the whole locker into one loan because the officer is in a hurry.
- Photograph items and note approximate weights.
- Get Gold valuer to test and weigh first if the lot is mixed or unmarked.
- Compare three numbers: independent metal value, lender assessed value, lender loan offer.
- Ask what happens if gold prices fall and LTV is reviewed.
- Ask whether you can repay early and collect the same packets.
- If the loan offer is far below a transparent sale figure and you do not need the jewellery back, sell. Do not pledge out of habit.
Haldwani customers searching sell gold near me often already know the jewellery will not be redeemed. Say that out loud. Then use gold buyers in Haldwani instead of a pledge you will abandon.
When Gold valuer Tells You to Sell Instead of Pledge
Gold valuer promotes sale when:
- The set is broken, unmatched, or out of wear
- Siblings need a split more than a pledged packet
- Medical or business cash is needed without EMI risk
- The borrower already has loans
- The only reason for a gold loan is that a jeweller exchange looked worse
Remember the retail trap as well. A jewellery shop exchange is not gold-for-gold at full value. Shops often apply a lower buy-back rate, deduct making or wastage on the old piece, then add making charges on a new piece. A bank loan is a different machine, but it also refuses making charges. The common lesson is the same: price the metal first. Gold valuer is the Haldwani table for that price.
Sell Gold in Haldwani After You Understand the Loan Math
Suppose a lot is assessed by a lender at a reference-linked value and the branch offers 75% to 85% of that, depending on ticket size. Interest then sits on the amount you take. If twelve months later you cannot close, auction rules apply. If you could have sold the same lot through Gold valuer and kept the proceeds without tenure, the “cheap loan” was only cheap on day one.
That is the promotional point, and it is fair. Loans are useful. They are not automatic. Sale is useful. It is final. Choose with a valuation in hand.
The Haldwani Close
Banks and NBFCs use gold valuation to protect themselves: eligible ornaments, tested purity, net weight, reference rate, LTV. You should use gold valuation to protect yourself: independent test, written breakup, a clear choice between pledge and sale.
If you need the jewellery back, take the loan with your eyes open.
If you need money and not a packet in a vault, come to Gold valuer for cash for gold in Haldwani.
Do not let the first gold-loan board on the road become your only valuer. Search gold buyers in Haldwani until you find a desk that shows purity and weight. When you type sell gold near me, you are already closer to a sale than to a pledge. Sell gold in Haldwani through Gold valuer when that is the safer product — rate, purity, weight, payment — and keep lender math for the day you truly want the gold home again.